The taxation of a plot in a leisure residential park (PRL) does not overlap with that of a traditional building plot or a camping site. Between registration fees, VAT, property tax, and capital gains regime, the applicable rules vary depending on the exact nature of the transaction and the status of the buyer. Understanding these differences before signing helps avoid additional costs that most buyers discover too late.
VAT or registration fees on a PRL plot: two regimes that do not accumulate
The first trap lies in the fiscal nature of the transaction itself. Buying a plot in a PRL can fall under either real estate VAT or registration fees, depending on whether the seller is a professional liable for VAT or a private individual, and whether the plot is classified as a building land or not.
| Criteria | Sale by a liable professional | Sale between individuals |
|---|---|---|
| Main regime | Real estate VAT (normal rate) | Registration fees |
| Base | Total sale price | Sale price or market value |
| Transfer duties | Reduced rate (subject to conditions) | Full departmental rate |
| VAT recovery by the buyer | Possible if rental activity is liable | Not applicable |
The qualification of building land, in fiscal terms, does not depend solely on the classification as a PRL. Administrative jurisprudence reminds us that the qualification must be articulated with the concrete characteristics of the transaction. A plot sold with a mobile home already installed may receive different treatment than an empty plot.
Many buyers discover this point at the time of signing with the notary. The seller announces a “TTC” price without specifying the applicable regime, and the buyer finds themselves facing a notarial cost different from what was anticipated. Asking the notary, before any compromise, to explicitly qualify the fiscal regime of the sale remains the most direct precaution.
Several buyers confronted with the taxation when purchasing a PRL plot find that this distinction between VAT and registration fees almost never appears in the commercial documents of the manager.
Property tax and residence tax in PRL: a variable fiscal treatment
The most widespread confusion concerns local taxes. Some PRL managers present the purchase of a plot as a way to escape residence tax on secondary homes. The reality is more nuanced.
The residence tax remains due on secondary homes, including when they are located in a PRL. The gradual elimination of this tax has only concerned primary residences. A mobile home or chalet occupied as a secondary residence in a PRL remains subject to this tax in the majority of municipalities.
For property tax, the treatment varies depending on whether the buyer owns the land or is merely a holder of a usage right. In a PRL with plot transfer, the buyer becomes liable for property tax like any landowner. In contrast, in a PRL under hotel regime (without land transfer), it is the operator who bears this charge, which is then passed on in the annual charges.
- PRL with plot transfer: property tax charged to the buyer, calculated on the cadastral rental value of the land
- PRL under rental regime: property tax borne by the operator, but included in the annual charges billed to the resident
- Residence tax on secondary residence: due by the occupant in both cases, with possible surcharge in certain tight areas
The difference between these two configurations can represent several hundred euros per year. Asking the manager for a detailed breakdown of local taxes, municipality by municipality, allows for a real comparison of the cost of occupation.
Capital gains tax and resale of a PRL plot: often ignored rules
The resale of a plot in a PRL is subject to the capital gains tax regime for individuals, with a progressive allowance depending on the duration of ownership. This point is rarely addressed during the purchase, as the prospect of resale seems distant.
The total exemption from capital gains only occurs after twenty-two years of ownership for income tax, and thirty years for social contributions. However, the average duration of ownership of a PRL plot is often much shorter, especially when the owner sells for health reasons or a change in leisure plans.
Another underestimated aspect concerns the actual valuation of the property. Unlike an apartment or a house, a PRL plot suffers a significant depreciation upon resale. The liquidity of this type of property is low, with the secondary market being restricted. Therefore, the calculation of taxable capital gains may seem theoretical when the resale value stagnates or decreases.
Inheritance tax on a PRL plot
In the event of the owner’s death, the plot enters the estate just like a traditional real estate asset. Inheritance tax applies to the market value on the day of death. This information surprises families who considered the purchase in a PRL as a leisure investment without patrimonial consequences.
The standard allowances for direct line apply, but the market value of a PRL plot is sometimes difficult to establish due to the lack of comparable transactions in the same park. The tax administration may retain an estimate different from that of the notary, which opens the door to adjustments.
Rental operation of a chalet in PRL: distinguishing acquisition tax and income tax
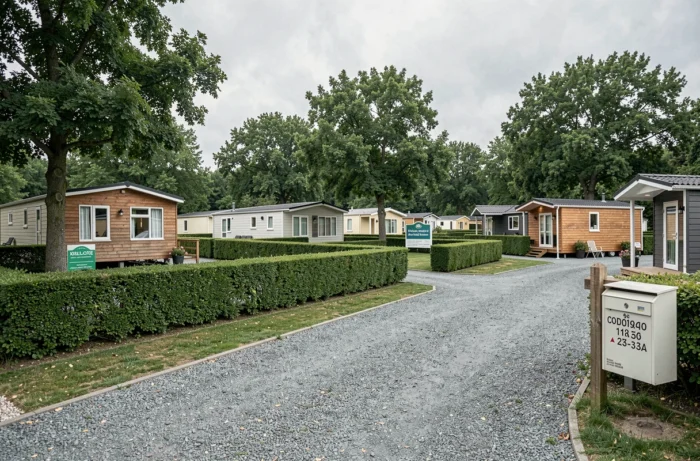
Renting out your chalet or mobile home on a PRL plot generates taxable income. The applicable regime (micro-BIC or real) depends on the amount of revenue and the chosen status. This fiscal aspect is distinct from that of the acquisition, but the two interact.
A buyer who purchases through a VAT-liable professional can, under certain conditions, recover VAT on the purchase price if they engage in a furnished rental activity with para-hotel services. This recovery requires maintaining the rental activity for several years; otherwise, a proportional VAT repayment is required.
- Micro-BIC regime: flat-rate allowance on revenue, simplicity in declaration, but no deduction of actual charges
- Real regime: deduction of depreciation, maintenance charges, and loan interest, but heavier accounting obligations
- VAT commitment: possible recovery at purchase, but obligation to maintain rental activity under penalty of repayment
The choice of tax regime conditions the net profitability of the investment over the entire holding period. An arbitration made only at the time of purchase, without projection over time, exposes one to costly tax corrections.
The taxation of a PRL plot involves rules borrowed from real estate law, the tourism code, and the regime of furnished rentals. None of these frameworks apply fully, and it is precisely this overlap that creates the traps. Getting a notary or tax advisor to quantify the overall tax cost, including acquisition, holding, and exit, remains the only reliable way to assess the economic reality of the operation.